For over a decade, Burial Senior Insurance has helped seniors and families nationwide plan ahead with honest, affordable final expense coverage — no medical exams, no waiting periods, and no pressure. Our licensed agents guide you to the plan that fits your budget and your family’s needs.
Families Protected
Average Client Rating
Top-Rated Carriers
Average Approval Time
30+
years helping families plan ahead
Variable Universal Life (VUL) insurance is a permanent life insurance policy that pairs flexible death benefit protection with investment sub-accounts similar to mutual funds. It allows policyholders to directly invest their accumulated cash value in stocks, bonds, and money market funds to maximize long-term wealth accumulation.
Unlike traditional whole life or indexed universal life policies, VUL offers uncapped growth potential tied directly to sub-account performance. In exchange for market upside, the policyholder assumes the market risk—making it a dynamic financial tool for experienced investors seeking tax-free capital growth alongside permanent insurance.
Harness market momentum to build wealth inside a tax-sheltered life insurance structure.
Cash value earnings are tied directly to underlying fund performance with no earnings cap.
Rebalance and trade between sub-accounts without triggering annual capital gains taxes.
Access accumulated cash value through tax-free policy loans and withdrawals during retirement.
Adjust your premium contributions within policy limits based on investment goals and cash flow.
Choose from professionally managed stock, bond, real estate, and fixed-income sub-accounts.
Maintain lifelong death benefit coverage to preserve family wealth and estate continuity.
Customize your portfolio allocation based on your risk tolerance and long-term financial goals.
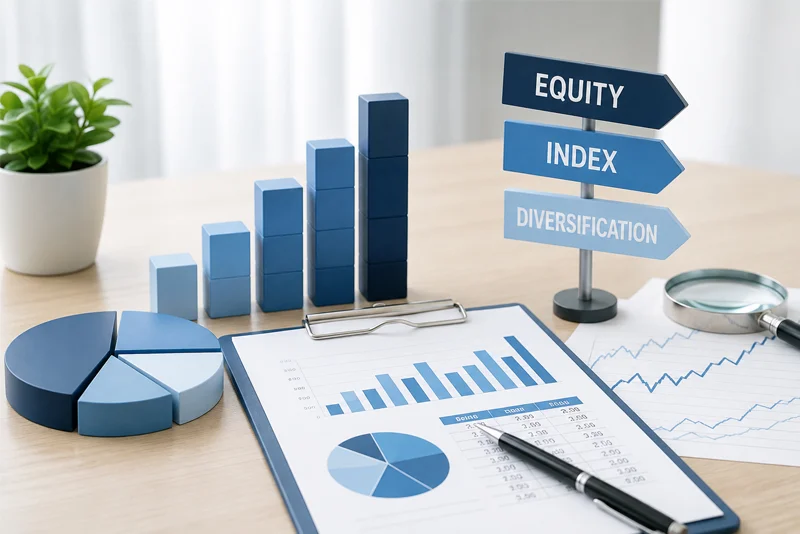
Directs cash value into large-cap, mid-cap, international, and tech sector investment funds for maximum long-term capital appreciation.
Spreads cash value across a mix of stocks and corporate/government bond funds to smooth out market volatility.
Allocates funds primarily to guaranteed interest fixed accounts and high-quality short-term debt instruments.
Designed for market-savvy investors seeking tax-advantaged wealth expansion.
Individuals maxing out traditional 401(k) and IRA limits who need additional tax-sheltered investment space.
Savers comfortable with market fluctuations who want direct control over their fund options.
Professionals building an aggressive tax-free cash reserve for supplemental retirement income.
Families transferring wealth tax-free to heirs while compounding investment returns.
Entrepreneurs looking for high-liquidity cash value accounts to collateralize business expansion.
Parents building significant multi-decade funds for child education or wealth creation.
Variable Universal Life insurance bridges the gap between active market investing and permanent financial protection. Unlike Indexed Universal Life (IUL), which caps your upside returns in exchange for a 0% floor guarantee, VUL allows your cash value to capture the full, uncapped return of underlying equity markets.
Because cash value growth inside a VUL is sheltered from annual income taxes and capital gains tax, your investments compound significantly faster than equivalent taxable brokerage accounts—allowing you to leverage policy loans for tax-free retirement income.
Distinct features engineered for risk protection, flexibility, and wealth building.
No medical physicals or blood tests required during conversion.
Retain your original medical health rating (e.g., Preferred Plus) upon converting.
Exercise your right to convert at any point during your policy's conversion period.
High coverage limits available for minimal initial monthly premiums.
Converted permanent policies generate accessible equity over time.
Beneficiaries receive the cash payout free of federal income taxes.
(800) 718-4568
Simple steps from locking in term rates to activating permanent lifetime security.
1
Select your term length (e.g., 20 Years) and starting coverage amount.
2
Enjoy predictable, fixed low monthly rates during your initial policy period.
3
Answer quick health and financial questions online or over the phone.
4
Your new whole life rate locks in for life without taking any medical exam.
Evaluate how VUL differs from Guaranteed Universal Life and Indexed Universal Life.
|
FEATURE
|
GUARANTEED UNIVERSAL LIFE (GUL)
|
INDEXED UNIVERSAL LIFE (IUL)
|
VARIABLE UNIVERSAL LIFE (VUL)
|
|---|---|---|---|
|
Primary Goal
|
Pure Lifetime Death Benefit
|
Balanced Growth with 0% Floor
|
Maximum Uncapped Growth
|
|
Investment Exposure
|
None (Fixed)
|
Stock Market Index (Capped)
|
Direct Funds / Stocks / Bonds
|
|
Downside Risk
|
Zero Risk
|
Zero Risk (0% Guaranteed Floor)
|
Market Downside Exposure
|
|
Upside Potential
|
Fixed Rate
|
Moderate (Subject to Caps)
|
Uncapped Market Performance
|
|
Premium Flexibility
|
Low / Fixed
|
High
|
High
|
VUL delivers the highest long-term growth ceiling among permanent life insurance options, making it ideal for investors comfortable managing market volatility.
We help you structure VUL policies properly to keep internal costs low and investment performance high.
Policy designs focused on reducing internal insurance charges to maximize investment growth.
Partner with top-rated insurance carriers featuring premier fund managers (Vanguard, BlackRock, Fidelity).
Realistic performance modeling across various market market cycles.
Ongoing guidance to optimize sub-account allocations over your lifetime.
Start with a few basic details — takes less than a minute.
945+ Reviews
Or Call: (800)-718-4568
Answer a few quick questions and one of our licensed agents will help you compare real quotes from top-rated carriers — no obligation, no pressure.
✓ 100% Free Quote
✓ No Obligation
✓ Licensed Agents
IUL policies credit interest based on index changes with caps (e.g., max 9%) and a 0% loss floor. VUL policies invest cash directly into sub-accounts with no upside caps, but you bear the downside risk if market funds perform poorly.
Yes. Because your cash value is invested directly in market sub-accounts, negative market performance will decrease your cash balance. Proper funding and long-term asset allocation help cushion market downturns.
No. Reallocating or switching money between sub-accounts within a VUL policy is completely non-taxable, allowing you to rebalance your portfolio without triggering capital gains taxes.
You can access accumulated cash value through tax-free policy loans or tax-free withdrawals up to your policy cost basis (the total amount of premiums paid in).
Yes. VUL offers flexible premiums. As long as your accumulated cash value is high enough to cover mandatory internal policy charges, you can adjust, decrease, or temporarily pause premium payments.
Have Any Questions? Ask us anything — we’d love to answer!
Burial Senior Insurance provides information and services related to burial insurance for senior citizens, including policy options and end-of-life support services.
Copyright © Burial Senior Insurance 2026. All Right Reserved.