For over a decade, Burial Senior Insurance has helped seniors and families nationwide plan ahead with honest, affordable final expense coverage — no medical exams, no waiting periods, and no pressure. Our licensed agents guide you to the plan that fits your budget and your family’s needs.
Last Updated on: September 2nd, 2026
Reviewed by Kyle Wilson
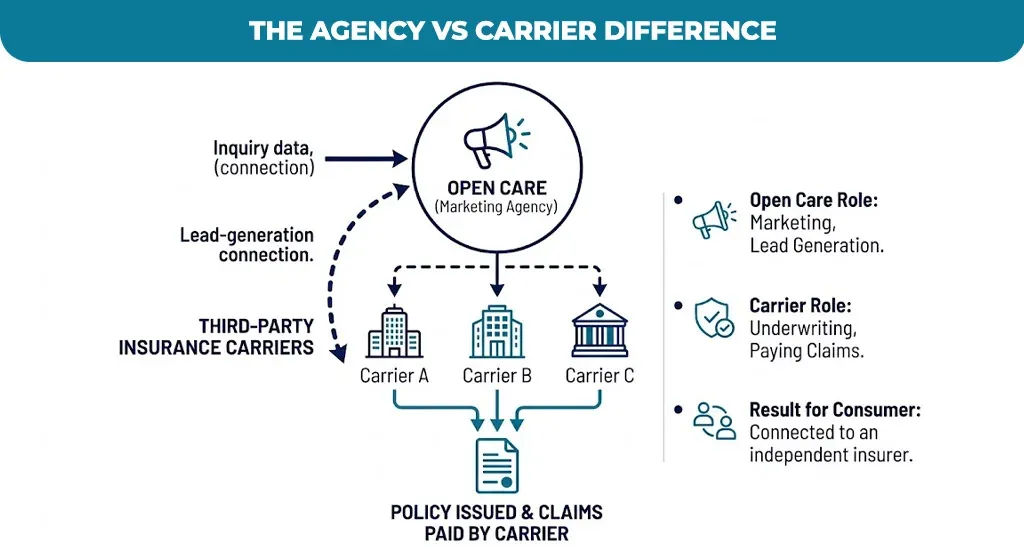
Open Care is one of the most heavily advertised names in senior final expense insurance, with ads promising rates as low as “$7.49 per month” and coverage with “no medical exam.” What those ads don’t make obvious up front is that Open Care isn’t actually an insurance carrier, it’s an independent marketing agency that connects consumers with third-party insurers who underwrite the policy and pay the claim. This review breaks down how Open Care actually works, what coverage really costs, what complaints show up most often, and how it stacks up against comparing carriers independently.
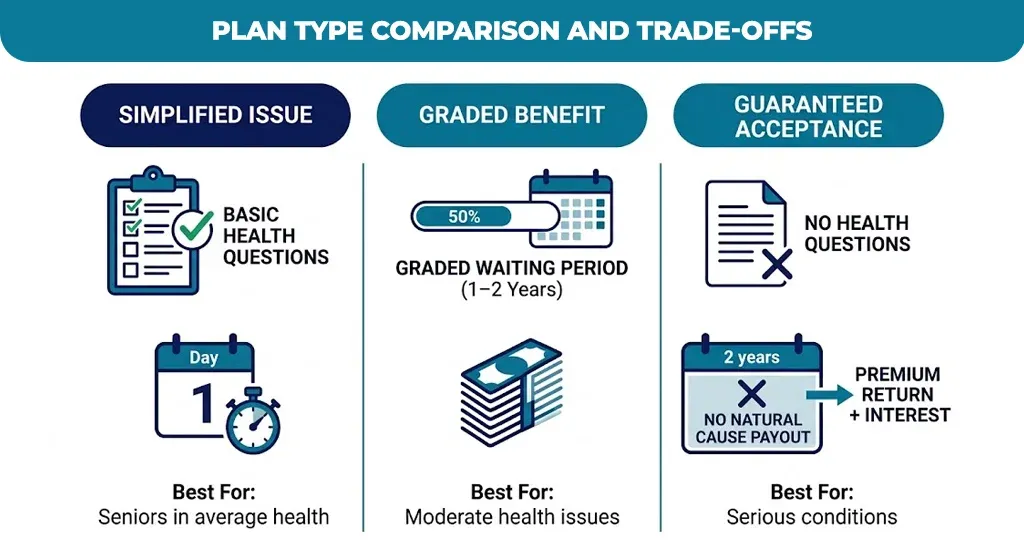
Open Care’s partner carriers generally offer coverage through a small handful of plan structures:
| Policy Type | Medical Exam | Health Questions | Waiting Period | Best For |
| Simplified Issue (Level) | None | Yes (5–10 basic questions) | None (Day 1 coverage) | Seniors in average to good health seeking lower rates |
| Graded Benefit Plan | None | Yes (includes minor conditions) | Partial payout (1–2 years) | Seniors with moderate health issues |
| Guaranteed Issue | None | None | 2-year waiting period (return of premium + interest) | Seniors with more serious pre-existing conditions |
Get Free Quotes
Customized Options Await
Sample rate table ($10,000 level benefit whole life estimate):
| Age & Gender | Monthly Cost (Non-Smoker) | Monthly Cost (Smoker) |
| Age 60 Male | $40 – $52 | $60 – $80 |
| Age 60 Female | $32 – $42 | $48 – $65 |
| Age 70 Male | $65 – $88 | $95 – $130 |
| Age 70 Female | $50 – $68 | $72 – $98 |
| Age 80 Male | $120 – $165 | $175 – $230 |
| Age 80 Female | $92 – $128 | $130 – $175 |
These are general planning ranges, not guaranteed quotes; actual pricing depends on which carrier ultimately issues the policy and the applicant’s specific health answers.
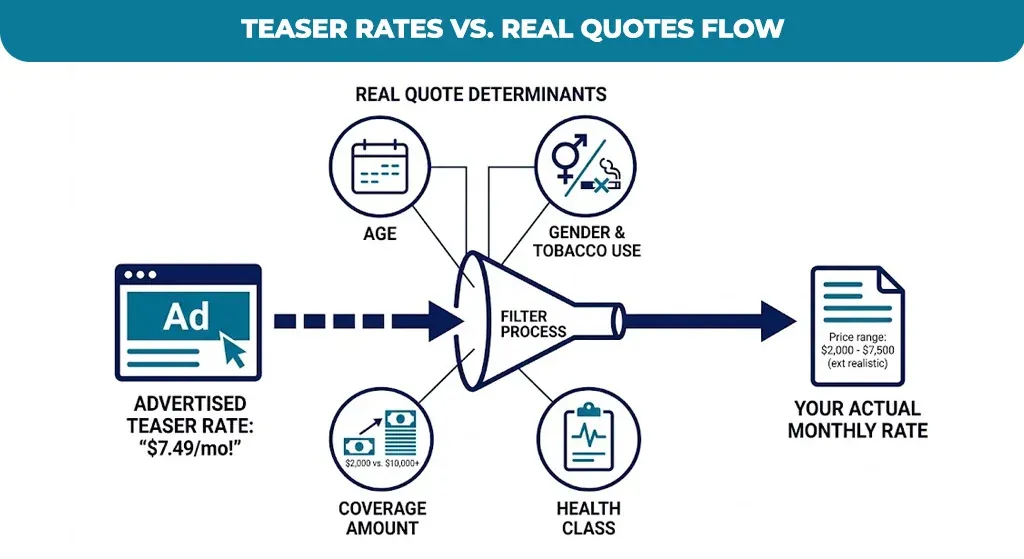
This is where Burial Senior Insurance takes a different approach than a broad lead-generation platform. Rather than funneling every caller into a generic queue, Burial Senior Insurance advisors compare rates across multiple top-rated carriers directly, so you know upfront which company is issuing your policy and what your actual monthly rate will be, based on your real health profile rather than a teaser ad.
Open Care does offer access to legitimate final expense policies through real, licensed third-party carriers but its advertising can create real confusion about actual monthly costs and which company you’re ultimately signing with. Seniors shopping for burial insurance deserve clear, upfront answers about pricing and underwriting before they enroll.
Burial Senior Insurance operates as an independent agency focused on putting your family’s needs first. Rather than routing you into a generic lead queue, experienced advisors compare top-rated life insurance carriers across the country to find locked-in rates and, where your health allows, immediate Day 1 coverage tailored to your actual profile. Contact Burial Senior Insurance today for a free, personalized senior life insurance quote.
Open Care is a legitimate licensed marketing agency and brokerage, but it is not an insurance carrier itself. It connects consumers with third-party life insurance companies that actually issue policies, handle underwriting, and pay out death benefits.
While ads feature rates starting around $7.49 per month, that reflects minimal coverage for a young, healthy applicant. Realistic costs depend heavily on age, gender, health, and coverage amount. A standard $10,000 final expense policy for a 70-year-old generally runs somewhere between roughly $50 and $88 per month.
Yes. The policies offered through Open Care's partner carriers are typically simplified issues (health questions, no exam) or guaranteed issues (no health questions and no exam).
Guaranteed issue plans accept applicants regardless of health, but they include a mandatory two-year graded waiting period. If the insured passes away from natural causes during that window, beneficiaries typically receive a return of premiums paid plus interest rather than the full death benefit.
When purchasing through a brokerage or lead platform like Open Care, your formal policy paperwork, monthly billing statements, and any claim documents will display the name and contact information of the actual underwriting insurance carrier. It's worth confirming this detail before you finalize enrollment.
Senior Writer & Licensed Life Insurance Agent
Jazmine Cooke is a dynamic and insightful senior writer with a passion for life insurance and financial planning. With over 8 years of hands-on experience in the insurance industry, Jazmine Cooke has earned a reputation for delivering clear, actionable advice that empowers individuals to make informed decisions about their financial future. At Burial Senior Insurance, she not only excels as a licensed insurance agent but also as a trusted guide who has successfully advised over +1500 clients, helping them navigate the often complex world of life insurance and annuities. Her articles have been featured in top-tier financial publications, making her a respected voice in the industry.
Have Any Questions? Ask us anything — we’d love to answer!
Burial Senior Insurance provides information and services related to burial insurance for senior citizens, including policy options and end-of-life support services.
Copyright © Burial Senior Insurance 2026. All Right Reserved.